Buying off the plan means agreeing to purchase a property before construction has been completed.
For some buyers, it can be a great way to secure a new home earlier in the process, while allowing more time before settlement. There are, however, a few extra things to understand before committing to the purchase.
When buying off the plan, you’re purchasing a property based on plans, specifications and inclusions rather than a completed home.
A deposit is generally paid when contracts are exchanged, with the remaining purchase price due once construction is complete and the property is ready to settle.
Because settlement may be months — or sometimes years — away, your circumstances, lending options and the property market can change during that time.
Buying early can give you the opportunity to secure a property before construction is finished and, depending on the development, you may also have some choice over finishes, layouts or inclusions.
The time between signing the contract and settlement can also give you more time to continue saving and prepare for the costs involved in completing the purchase.
It’s important to remember that your finance will generally need to be reviewed again closer to settlement.
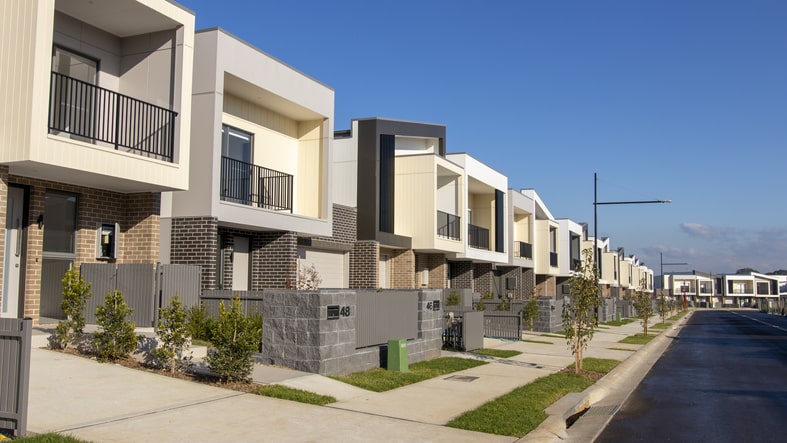
Off-the-plan contracts can be different from contracts for established properties, so it’s important to understand exactly what you’re agreeing to.
Your contract should outline things such as the purchase price, deposit, expected completion timeframe, property specifications and any conditions that may apply if the development is delayed or does not proceed.
Before signing, it’s a good idea to have the contract reviewed by your solicitor or conveyancer so you understand your rights and obligations.
One of the biggest advantages of buying off the plan is time. Unlike traditional property purchases with relatively short windows to round up the total finance, you will have at least 12 months, if not longer, to settle. Savvy buyers will take advantage of this extra time to save their pennies and reduce their borrowings.
If you dream of a new home but have nightmares at the thought of building one, an off-the-plan purchase may be the perfect compromise. Although you will not get to design everything as you would with a custom-built home, most off-the-plan developments allow some customisation of finishes and fixtures. Make sure your contract outlines what you can tailor and that you are clear on any additional costs.
Various incentives are still being dangled in front of first home buyers, which may add to the appeal of buying off the plan.
Concessions vary across Australia, so visit your State or Territory website (or simply talk to a mortgage broker) for the latest information on grants and exemptions. You can also research your eligibility for stamp duty concessions on new properties using our Stamp Duty Calculator.
Off-the-plan apartments are often pitched heavily at investors due to the tax benefits that come with depreciation on new properties and rental guarantees. Tax savings will depend on your individual circumstances, but generally the newer the property, the higher the depreciation allowance for the building and fixtures.
Investors may also be offered attractive rental guarantees for a limited period. Make sure you do your homework on rental returns on similar properties in the area before accepting the developer’s terms. Be wary of over-inflated rental guarantees. Builders will sometimes promise a high-rent yield to lure investors, build the cost into the property price and then subsidise any gap themselves for a short period. When the rental guarantee expires, you may find the actual market rent falls well short of what you originally pocketed. If investing, make sure you have the option to manage the property yourself or with your chosen property manager from the time you take possession.
Many buyers get swept up on a wave of rising property prices when they hand over their deposit in exchange for a floor plan. Historically, property is a consistent long-term performer, but property prices can plateau and even wane at the mercy of economic factors.
Buyers also need to be wary of over-supply, which may devalue their property.
Make sure you consider the bigger picture when buying off the plan. Research how many other developments are planned in the area and whether any increase in apartment numbers is justified by new or improved infrastructure, such as transport corridors, business precincts, universities or hospitals.
Make sure you purchase from a reputable builder and take the time to research their previous projects. Do they use quality contractors? Do they deliver projects on time? Make a point of visiting some of their projects, so you can assess the finished product first-hand.
Whether you’re buying, refinancing or just want to know your options, we are here to help make it simple.
Send through a quick enquiry and we’ll be in touch.